
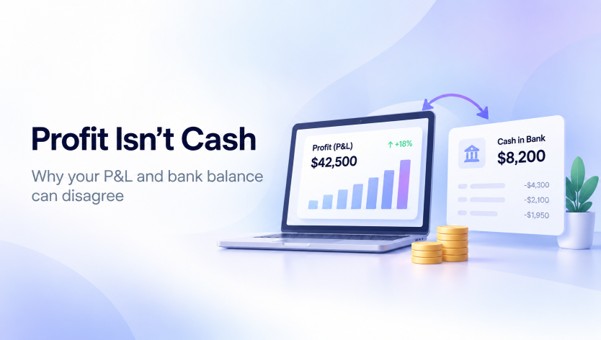
If your P&L says you made money this month and your bank balance disagrees, neither one is lying – they’re just not measuring the same thing. Profit is an accounting measure of what you’ve earned; cash flow is what has actually moved through your bank account. For growing businesses, looking at these numbers together is important because revenue, expenses, profitability and cash availability can move differently over time. Financial forecasting software can help bring these figures into one connected view instead of managing them across separate spreadsheets.Understanding exactly where the two diverge is what tells you whether your business has a growth problem or a timing problem.
For businesses that want to look beyond individual reports, AI financial planning can connect cash flow, profitability, forecasts and financial statements in one financial model.
Table of Contents
Why Does My P&l Show a Profit While My Bank Account Doesn’t Agree?
Because your P&L counts revenue when it’s earned, not when it’s collected, and it counts some costs (like depreciation) that never move cash at all. If you invoice a client in September but don’t get paid until November, that revenue shows up on September’s P&L – and boosts your “profit” – while your bank account stays exactly where it was. The larger your outstanding invoices, the wider this gap gets.
A quick example: you invoice $20,000 in September, spend $15,000 on costs already paid in cash, and your client pays in November. September’s P&L shows a $5,000 profit. September’s bank balance shows $15,000 less cash than it started with. Both are correct – they’re just answering different questions.
What Causes the Gap?
Four things, almost always
- unpaid receivables (revenue you’ve earned but not collected)
- inventory you’ve paid for but not yet sold
- loan principal payments (which reduce cash but don’t touch the P&L at all)
- one-time capital purchases like equipment.
None of these are wrong or alarming on their own – they’re normal parts of running a business. The problem is when founders read “profitable” on the P&L and assume that means “cash available,” and spend accordingly.
Which Statement Should You Trust for Decisions?
Both, for different decisions. The P&L tells you whether the underlying business model works – are you charging enough to cover your costs. The cash flow statement tells you whether you can make payroll next month. A founder deciding whether to hire should look at the P&L trend; a founder deciding whether they can afford to hire right now needs the cash flow statement.
The same financial information can also become important when assessing business value, particularly when cash flow and future projections are used as part of a valuation. Confusing the two is one of the more common ways otherwise healthy businesses hit a cash crunch – the same blind spot that shows up when founders skip the cash-position check before Q4 budget planning.
How Do You Close the Gap Between the Two?
Track days sales outstanding (how long it takes customers to pay you) and watch it monthly – a rising number is an early warning that your “profit” is getting less liquid. Build a simple 13-week rolling cash forecast alongside your P&L, not instead of it. And know your break-even point in cash terms, not just accounting terms – the break-even number that tells you whether your pricing works also tells you roughly how much cash cushion you need while receivables catch up.
What Should You Check First if This Is Happening to You Right Now?
Pull your accounts receivable aging report and see how much more than 30 days is overdue – that’s usually where the gap is hiding. Then check whether your cash flow statement has a clear reconciling line explaining the difference from your P&L; if it doesn’t, that’s the first thing to fix, because a business that can’t explain its own cash gap can’t forecast it either.
Reconciling the two takes more than a glance at a bank balance – it means your P&L, balance sheet, and cash flow statement all need to talk to each other. That’s whatVedaOne’s AI-powered financial planning tools are built to do: guided inputs that generate all three statements together, so the gap between “profitable” and “cash in the bank” is visible before it becomes a surprise.
Disclaimer:
This article is for educational purposes only. Financial projections are estimates based on assumptions. They should not be treated as guaranteed outcomes or as financial, tax, investment, or accounting advice. For high-stakes decisions, businesses should consult a qualified finance, accounting, or tax professional.
Frequently Asked Questions
Yes – unpaid receivables, loan payments, and inventory purchases can drain cash even when the P&L shows a profit.
Unpaid customer invoices (accounts receivable) are the most common cause for growing businesses.
Both – profit shows if the model works; cash flow shows if you can pay your bills this month.